Business tax planning strategies work best when reviewed throughout the year: choose the right entity, project tax quarterly, time income and deductions, use eligible retirement and depreciation provisions, document deductions, and monitor state filing obligations. The right combination depends on the taxpayer, business structure, tax year, and jurisdiction.
Tax planning has become more consequential because corporate tax rates and filing rules have shifted materially over time. The average statutory corporate income tax rate across OECD countries fell from 33.6% in 2000 to 28.4% in 2006, then declined to 23.2% by 2021, according to the Small Business & Entrepreneurship Council's discussion of OECD and U.S. tax-rate changes. In the United States, the combined federal-state statutory corporate rate remained around 39% from 2000 through 2017 before falling to 25.8% after the Tax Cuts and Jobs Act took effect, based on the same source.
That history explains why April-only planning isn't enough. This guide organizes 10 business tax planning strategies around entity structure, quarterly forecasting, timing, assets, retirement plans, charitable giving, and federal, New York, New Jersey, and multi-state compliance. Each strategy addresses who may benefit, how to implement it, when to act, what could change the tax result, common pitfalls, and when Blue Sage Tax and Accounting Inc., an accounting firm based in Bayside, Queens, should be involved. Tax figures, elections, deadlines, and deductions must be verified for the applicable 2026 tax year and jurisdiction.
Table of Contents
- 1. Should I use an S corporation and how should I set my salary?
- 2. Should I use quarterly tax projections instead of waiting for filing season?
- 3. How should I document home office and vehicle deductions?
- 4. Should I change my LLC or sole-proprietor tax structure?
- 5. When does accelerated depreciation or cost segregation make sense?
- 6. Do I need to file in both New York and New Jersey?
- 7. Which retirement plan fits an owner's income and workforce?
- 8. When should I accelerate deductions or defer income?
- 9. Can charitable giving reduce taxable income in a high-income year?
- 10. What documentation is required for large non-cash gifts?
- 10-Point Comparison of Business Tax Planning Strategies
- What should I review before the tax year ends?
1. Should I use an S corporation and how should I set my salary?
An S corporation can separate owner compensation into payroll wages and distributions, but the owner must receive reasonable compensation for services first. The IRS ties that compensation to the work performed, not to a fixed salary-to-distribution formula, as explained in this guidance on S corporation reasonable compensation.
A contractor with $600,000 in annual revenue and $250,000 in net profit might model a $120,000 salary and $130,000 distribution, but that split isn't automatically acceptable. The owner should compare the salary with duties, industry roles, geographic labor conditions, hours, credentials, and the company's ability to pay. Payroll taxes apply to wages, while distributions generally aren't subject to self-employment tax, but an artificially low salary can create payroll, penalty, and audit exposure.
How should an owner implement the strategy?
Start with a compensation analysis before making the election or changing payroll. Document the owner's duties and supporting market evidence, then run payroll consistently throughout the year. Sporadic wages, large year-end adjustments, or distributions taken while payroll is missing can undermine the position.
A contractor or professional practice with material net income may benefit from reviewing the structure. A dental practice in Queens, for example, needs to coordinate owner compensation with New York State and New York City obligations, payroll filings, and any professional-entity restrictions. A transportation company owner in New Jersey also needs to consider state treatment and multi-state payroll.
The practical question isn't whether distributions are attractive. It's whether the projected payroll, administrative cost, state treatment, and documentation support the structure.
Read Blue Sage Tax and Accounting Inc.’s explanation of what reasonable compensation means before changing owner payroll, then consult the firm before an election, conversion, or compensation adjustment.
2. Should I use quarterly tax projections instead of waiting for filing season?
Yes. Quarterly projections convert changing revenue, expenses, payroll, and estimated payments into a current view of the likely annual tax position. They also give owners time to act before year-end, rather than discovering an unexpected balance when the return is prepared.
A contractor might report $45,000 of Q1 revenue and then $180,000 in Q3, creating a very different annual projection. A restaurant owner in Queens may need to increase an estimated payment after a strong summer, while a consultant may identify a planned equipment purchase before the final quarter. The projection doesn't guarantee a result. It shows which decisions may still affect the result.
What should the projection include?
Update books monthly, not just before quarterly payment dates. Review:
- Year-to-date profit: Reconcile bank accounts, credit cards, accounts receivable, inventory, and payroll.
- Business changes: Add new contracts, staffing changes, seasonal revenue, loans, vehicles, and equipment.
- Tax actions: Model bonuses, retirement contributions, asset purchases, entity changes, and charitable gifts.
- State exposure: Include New York State, New York City, New Jersey, and other states where the business may have filing obligations.
If the model shows a possible refund, the owner may be able to adjust future payments, subject to applicable safe-harbor rules and withholding requirements. If income rises, the owner may need to increase payments or revise payroll withholding.
Blue Sage Tax and Accounting Inc. provides quarterly estimated tax planning tools, but a calculator can't replace a projection based on complete books. Bring the firm into the process during the year, especially around months nine and ten, when bonus, asset, retirement, and entity decisions may still be practical.
3. How should I document home office and vehicle deductions?
Use the method that fits the facts, then keep records that connect each expense to business activity. Self-employed taxpayers may generally choose between simplified and regular home-office methods, while vehicle deductions typically require a comparison of standard mileage and actual expenses.
A freelance consultant in Bayside with a dedicated 200-square-foot office might evaluate the simplified method, while a plumber with a 300-square-foot workshop may find the regular method more appropriate if business-use expenses are substantial. The result depends on exclusive business use, the space's eligibility, home expenses, and the taxpayer's records.
Vehicle planning requires the same discipline. A transportation owner tracking business miles should preserve dates, destinations, business purposes, and mileage. A mileage application such as MileIQ or Everlance can help capture trips, but the owner still needs to review the entries and separate commuting from business travel.
Which records matter most?
Keep a floor-area calculation, mortgage-interest and property-tax records, utilities, insurance, repairs, depreciation schedules, and evidence that the workspace is used regularly and exclusively for business. Under the regular method, mortgage interest and principal must be treated differently. A home office also can't be used to shelter unrelated losses because the deduction is available.
For vehicles, compare actual fuel, maintenance, insurance, depreciation, and lease costs with the applicable standard mileage method before committing to a method. The choice and future-method restrictions can depend on how the vehicle was first treated.
The tax impact may be meaningful for contractors and consultants, but weak documentation can erase the benefit. Blue Sage Tax and Accounting Inc. should review the method when a home office produces a loss, the vehicle is heavily used, or personal and business driving overlap.
4. Should I change my LLC or sole-proprietor tax structure?
Review entity structure whenever profit, liability exposure, ownership, or state activity changes. A sole proprietorship, LLC, S corporation, C corporation, and partnership can produce different payroll, income-tax, administrative, and filing outcomes, so conversion should follow a projection rather than a rule of thumb.
A contractor with $400,000 in revenue needs to distinguish revenue from net profit before considering an S corporation. A real estate investor in Queens may form an LLC for liability and ownership reasons while preserving pass-through tax treatment. A New Jersey transportation business may consider an S corporation only after modeling reasonable compensation, vehicle ownership, payroll, and multi-state filings.
What should owners compare?
Compare the following before filing an election:
- Federal treatment: How profits, losses, wages, distributions, and retained earnings are taxed.
- State treatment: New York and New Jersey may impose different filing requirements, fees, taxes, or conformity rules.
- Administration: Payroll, bookkeeping, shareholder reporting, separate accounts, and corporate records.
- Ownership: Whether new investors, multiple members, or family ownership could make partnership treatment more flexible.
- Industry limitations: Some states restrict entity options for medical, legal, accounting, and other professional practices.
A mid-year conversion can affect estimated payments, payroll, accounting periods, and state registrations. It may also create costs that outweigh a projected tax advantage when profits are modest or inconsistent.
Review the structure annually and whenever profits change materially. Blue Sage Tax and Accounting Inc. should model the federal and state consequences before an election is filed, particularly for owners operating between New York and New Jersey.
5. When does accelerated depreciation or cost segregation make sense?
Accelerated depreciation may improve near-term cash flow when a business buys qualifying equipment, improvements, or real property. Cost segregation can separate building components into different recovery categories, but it requires a defensible engineering and tax analysis rather than a simple deduction claim.
A Queens restaurant buying a building may evaluate the treatment of interior systems, HVAC, roofing, and other components. A contractor purchasing substantial equipment may compare available expensing and depreciation elections. A New Jersey real estate investor may study land improvements and equipment separately from the building structure.
The key decision is not “Can I deduct this quickly?” It's “Will the accelerated deduction help after considering current income, state conformity, passive-activity rules, future income, and recapture?”
What can go wrong?
Bonus depreciation, Section 179, and related elections change over time. Availability, limits, placed-in-service requirements, state conformity, and minimum-tax interactions must be checked for the 2026 tax year. A large first-year deduction may have limited value if the owner lacks sufficient taxable income or if passive activity rules suspend the loss.
Owners should preserve purchase documents, placed-in-service dates, invoices, title records, asset classifications, and any cost-segregation study. They should also model the future consequences of selling property, including depreciation recapture.
Practical rule: Don't buy equipment solely for a deduction. The asset should support an operating need, and the tax treatment should be evaluated after the cash-flow decision.
Cost segregation may be more practical for substantial commercial or rental property, while smaller purchases may not justify a study. Blue Sage Tax and Accounting Inc. should coordinate with the cost-segregation provider and review federal, New York, and New Jersey treatment before the purchase or election.
A visual model of the property components can help owners understand why different assets may receive different recovery treatment.
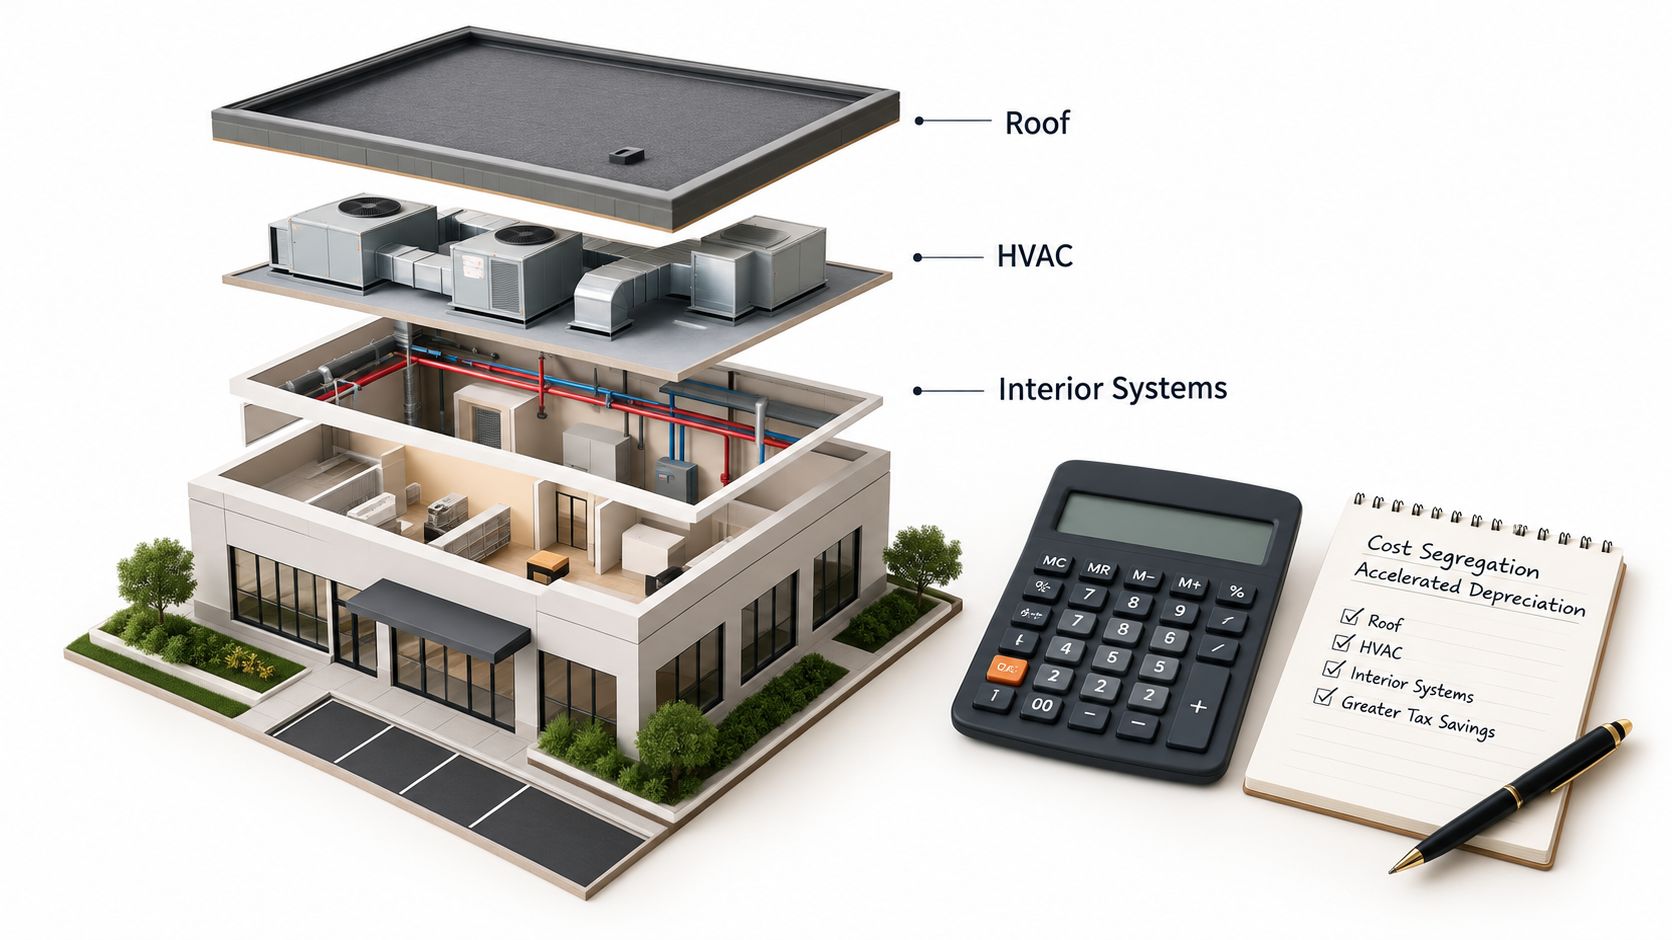
The election should fit the projection, not drive the purchase.
6. Do I need to file in both New York and New Jersey?
Possibly, and the answer depends on nexus, where services are performed, sales, payroll, property, entity structure, and each state's allocation rules. A business may need income-tax, payroll, sales-tax, or other filings even when it doesn't have a traditional office in the state.
A restaurant owner operating in Queens and another New York location must review entity and local reporting separately from a business operating across state lines. A contractor headquartered in Queens with work performed in New Jersey needs records showing where labor and property were used. A New Jersey transportation company with drivers crossing several states must track payroll, vehicles, and operating activity by jurisdiction.
How should multi-state owners prepare?
Maintain monthly state-level records rather than reconstructing them at year-end:
- Payroll allocation: Track where employees and drivers perform services.
- Property allocation: Record vehicles, equipment, offices, and inventory by location.
- Sales activity: Monitor customers, delivery destinations, and service locations.
- Entity relationships: Determine whether related entities may be included under combined-reporting rules.
- Local filings: Separate state requirements from New York City, county, and other local obligations.
Economic nexus thresholds differ by state and activity. Don't rely on a generic sales threshold without verifying the applicable rule for the tax year. Apportionment formulas also change, and some states place greater weight on sales than payroll or property.
State filing analysis should begin when a business signs a new contract, hires across state lines, buys property in another state, or expands delivery activity.
A restaurant owner in New York and New Jersey may need separate state analysis even when bookkeeping is centralized. Blue Sage Tax and Accounting Inc. can help reconcile the books to state returns, but owners should involve the firm before expansion, not after notices arrive.
7. Which retirement plan fits an owner's income and workforce?
A SEP-IRA, Solo 401(k), or defined-benefit plan may reduce current taxable income while funding retirement, but each option responds differently to variable income, employee participation, and administrative capacity. The best choice depends on the owner's earnings, workforce, cash flow, and willingness to maintain compliance.
A self-employed consultant with $200,000 of net self-employment income may compare employee deferrals and employer contributions under a Solo 401(k). A contractor with uneven income may prefer the flexibility of a SEP-IRA. A stable, high-income professional may investigate a defined-benefit plan, but actuarial work and ongoing funding commitments make it unsuitable for every business.
What should be decided before year-end?
Confirm whether the plan must be established before the end of the year, whether an employee deferral election is required before year-end, and when employer contributions can be made. Calculate contributions from accurate net self-employment income, not gross revenue. If the business hires employees, review eligibility and nondiscrimination requirements before using a plan designed for an owner-only business.
The deduction may reduce current taxable income, but it also commits cash to a retirement account and may create employee-cost obligations. A declining or unpredictable business shouldn't make a contribution it can't support because the deduction appears attractive.
Owners should coordinate the plan with S corporation wages, partnership income, payroll, and personal cash needs. Blue Sage Tax and Accounting Inc. should be consulted before a new plan is adopted, especially if income is above the level where a defined-benefit design might be considered or employees may participate.
8. When should I accelerate deductions or defer income?
Timing can shift taxable income between years for eligible cash-basis taxpayers, but it must reflect a genuine business transaction and a defensible accounting method. Accelerating a deduction may help in a high-income year, while deferring income may be useful when the next year is expected to have lower income, but neither choice is automatically beneficial.
A contractor with $400,000 in revenue and $300,000 in expenses might model whether invoices, bonuses, equipment, and discretionary expenses belong in the current year or the next. A consultant whose work is delivered on November 30 but requests payment in January must confirm when income is recognized under the applicable method. An S corporation owner also needs to distinguish payroll timing from distributions.
What should the owner document?
Run several scenarios during Q3 or early Q4, including a bonus, expense payment, retirement contribution, equipment purchase, or invoice change. Document the commercial reason in an internal memo, contract, invoice record, or email. An unusual timing pattern without a business purpose can invite questions.
Don't defer income merely to postpone tax if the business needs the cash now. Don't prepay expenses that don't qualify or buy unnecessary assets. Also consider estimated-payment rules, state conformity, payroll taxes, inventory accounting, and the possibility that the next year will be more profitable.
The impact is conditional. Timing often works best when the owner controls payment dates and has reliable projections. Blue Sage Tax and Accounting Inc. should model the options before the transaction occurs, not after the books are closed.
9. Can charitable giving reduce taxable income in a high-income year?
Charitable giving may support an income-tax deduction when the contribution qualifies, the taxpayer has sufficient income, and the substantiation and limitation rules are satisfied. A donor-advised fund can allow an owner to contribute appreciated assets or cash in a high-income year while recommending grants to charities over time.
A business owner with an unusually profitable year may compare a direct gift with a donor-advised fund contribution. The decision should consider the asset, fair market value, holding period, adjusted gross income limitations, carryforwards, liquidity, and the owner's charitable intentions. A deduction isn't the same as a reimbursement, and an irrevocable contribution removes the asset from the owner's control.
When does a donor-advised fund fit?
A DAF may suit an owner who wants to bunch several years of charitable intentions into one contribution year. Appreciated securities can raise additional valuation and substantiation questions, while cash gifts may be simpler. The owner should receive written acknowledgment, retain transfer records, and confirm that the recipient is an eligible organization.
The tax impact may be more useful in a year with substantial pass-through income, a business sale, equity compensation, or another large taxable event. It may be less compelling when the contribution strains operating liquidity or the owner would give the same amount regardless of tax treatment.
Owners should model charitable giving alongside retirement contributions, QBI eligibility, state deductions, and estimated payments. Blue Sage Tax and Accounting Inc. should review the planned contribution before transfer, especially when the gift involves appreciated property, a business interest, or a donor-advised fund.
10. What documentation is required for large non-cash gifts?
Large non-cash gifts require valuation and substantiation that match the property and contribution. Appreciated property and conservation easements can attract scrutiny, so owners should obtain qualified appraisals and complete the required reporting before claiming the deduction.
A contribution of publicly traded securities may have a clearer market value than privately held business interests, artwork, real estate, or a conservation easement. The donor must preserve transfer records, the recipient's acknowledgment, valuation support, and evidence that the contribution was completed in the claimed year. A qualified appraisal may be necessary, and the deduction can depend on holding period, property type, and adjusted gross income limitations.
How can owners reduce compliance risk?
Obtain the appraisal before filing, not after an examination begins. Review the valuation methodology, appraiser qualifications, ownership records, restrictions, and any related-party arrangements. Keep the reporting schedules and carryforward records when the applicable limitation prevents full use in the contribution year.
Conservation easements deserve legal review in addition to tax review. The transaction documents, conservation purpose, appraisal, property restrictions, and charitable recipient must align. A donor-advised fund can simplify ongoing grant recommendations, but the initial gift remains irrevocable and account fees may affect smaller donations.
A deduction is only as strong as the records supporting the amount, date, property, recipient, and valuation.
Blue Sage Tax and Accounting Inc. should coordinate with the taxpayer's attorney, appraiser, and financial professionals before a large non-cash contribution. The accounting firm can review the tax reporting and carryforward implications, but it doesn't provide legal services or appraisals.
10-Point Comparison of Business Tax Planning Strategies
| Strategy | 🔄 Implementation Complexity | 💡 Resource Requirements | ⭐ Expected Outcomes | 📊 Ideal Use Cases | ⚡ Key Advantages |
|---|---|---|---|---|---|
| S-Corporation Election and Reasonable Salary Strategy | Moderate–High: Form 2553, payroll setup, ongoing reasonable-salary documentation | Payroll system, accountant/bookkeeper, quarterly filings; state-specific elections | Significant SE tax savings on distributions if compliant; audit risk if salary unreasonable | Service businesses, contractors, professional practices with material net income | Lowers self-employment tax on distributions; retains liability protection |
| Quarterly Tax Projections and Estimated Payment Planning | Low–Moderate: recurring quarterly modeling and updates | Monthly bookkeeping, tax software or accountant time | Smoother cash flow; reduced underpayment penalties; better year-end visibility | Owners with uneven/seasonal income or volatile cash flow | Avoids surprise tax bills; enables proactive tax timing |
| Home Office and Vehicle Deduction Optimization | Low–Moderate: select method(s) and maintain contemporaneous records | Mileage log app, utility/expense records, possible appraisal/depreciation schedules | Material reduction in taxable income when properly documented; potential recapture on sale | Home-based businesses, high-mileage contractors, consultants | Flexible methods (simplified vs actual); combined vehicle and home savings |
| Business Entity Structure Review and Conversion Planning | High: legal formation/conversion, timing, state compliance differences | Legal and tax advisory, formation fees, payroll if S‑corp, conversion planning | Optimized tax/liability profile; possible SE tax savings but conversion costs | Growing businesses, those needing liability protection or multi-state ops | Aligns liability protection with tax planning; can reduce taxes via entity choice |
| Cost Segregation and Asset Depreciation Acceleration | High: requires engineering/cost study and tax allocation | Cost segregation study ($15k–$50k+), CPAs, appraisals; works best for larger properties | Large early-year deductions and improved cash flow; increased recapture risk on sale | Real estate investors, construction firms, manufacturers with large asset buys | Accelerates deductions (Section 179/bonus) to defer taxes and improve liquidity |
| Multi-State Income Apportionment and Combined Reporting | Very High: nexus determinations, varying apportionment formulas, combined reporting rules | Detailed payroll/property/sales tracking, multi-state filings, state tax counsel | Accurate state tax allocation; potential reduction in aggregate state tax with planning | Businesses operating across states (transport, multi-location retailers) | Avoids double taxation; optimizes apportionment to lower-tax states |
| Retirement Plan Contributions and Solo 401(k) Optimization | Moderate: plan setup, contribution calculations, compliance filings | Plan admin, payroll adjustments, actuarial services for defined benefit plans | Large current-year deductions and retirement savings; complex limits for high incomes | Self-employed or small-business owners wanting high retirement contributions | High contribution limits (Solo 401k/defined benefit); tax-deferral and loan options (Solo 401k) |
| Timing of Income and Deductions for Tax Year Optimization | Low–Moderate: requires deliberate year-end actions and documentation | Cash-basis bookkeeping, coordination with clients/vendors, tax modeling | Shifts taxable income between years to manage brackets and estimated tax | Cash-basis taxpayers with discretionary invoicing or payments | Immediate control over tax timing; smooths taxable income across years |
| Charitable Contributions and Donor-Advised Fund Strategies | Low–Moderate: DAF setup and appraisal process for non-cash gifts | DAF account fees, qualified appraisals for appreciated assets, recordkeeping | Income tax deduction, avoid capital gains on donated appreciated assets; bunching benefits | High-net-worth donors in high-income years, owners with appreciated securities | Avoids capital gains, enables bunching and phased grantmaking |
| Charitable Contribution Compliance, Appraisal and Substantiation Notes | Moderate–High: appraisal and substantiation requirements for large gifts | Qualified appraisals ($500–$2k+), Form 8283, legal counsel for easements | Defensible deduction claims and reduced audit/penalty risk when documented | Large non-cash donations, conservation easements, high-value property gifts | Ensures compliance and minimizes IRS challenge and penalties |
What should I review before the tax year ends?
Start with the books. Reconcile bank accounts, credit cards, payroll, loans, inventory, accounts receivable, and fixed assets so the projection reflects the business rather than incomplete records. A clean year-to-date ledger gives the owner a usable base for every later decision.
Next, run a federal projection and separate state analysis for 2026. Include New York State, New York City, New Jersey, and any other jurisdiction where the business has employees, property, customers, or service activity. Tax rules, thresholds, elections, and state conformity can change, and amounts that apply for one year may adjust annually.
Then review the decisions most likely to affect the year:
- Entity and payroll: Confirm whether the structure still fits the owner's profit, liability, and workforce.
- Compensation: Test S corporation wages against the services performed and document the analysis.
- Estimated payments: Compare payments with current projections and revise where permitted.
- Timing: Model income, bonuses, deductible expenses, and retirement contributions before payment dates.
- Assets: Evaluate whether an equipment purchase or depreciation election supports the business need.
- Retirement: Confirm plan establishment, employee coverage, contribution calculations, and cash capacity.
- Charity: Complete valuation, transfer, acknowledgment, and carryforward documentation before filing.
- Multi-state compliance: Track payroll, sales, property, nexus, apportionment, and combined-reporting requirements.
Don't treat every deduction as a win. A deduction can produce little current benefit when the business has insufficient taxable income, while an accelerated deduction may create a less favorable result in a future year or under a state's different rules. The same caution applies to retirement contributions, entity conversions, and charitable gifts. Their effect depends on income, cash flow, ownership, tax method, and jurisdiction.
Tariff and supply-chain exposure also belongs in the forecast for import-heavy retail, e-commerce, distribution, and manufacturing businesses. Recent business tax guidance for 2026 planning recommends incorporating tariff scenarios into cash-flow models and considering measures such as supply-chain diversification, the first sale rule, and foreign trade zones. Protecting margin and liquidity may matter more than pursuing a year-end write-off.
Likewise, research and development, depreciation, energy incentives, state conformity, and minimum-tax exposure should be reviewed together. 2026 planning guidance for accounting firms highlights the need to examine election-specific consequences and build corporate alternative minimum tax checks into quarterly planning rather than waiting until year-end.
Blue Sage Tax and Accounting Inc. offers year-round tax planning and quarterly projections, including mid-year and fourth-quarter modeling. The firm works with owner-operated businesses, self-employed professionals, contractors, transportation companies, restaurants, medical and dental practices, real estate investors, and multi-state filers. Complex matters such as S corporation compensation, cost segregation, charitable valuations, and multi-state apportionment warrant timely professional review because the tax impact is conditional and documentation matters.
Book your free consultation call today.
This article is general information and not tax advice for your specific situation.
Blue Sage Tax & Accounting Inc. provides year-round business tax planning, quarterly projections, entity selection, reasonable compensation analysis, retirement planning coordination, and multi-state filing support. Visit Blue Sage Tax & Accounting Inc. to discuss the decisions that should be modeled before the 2026 tax year ends and Book your free consultation call today.